Insights
- Private Sector - Financial Services
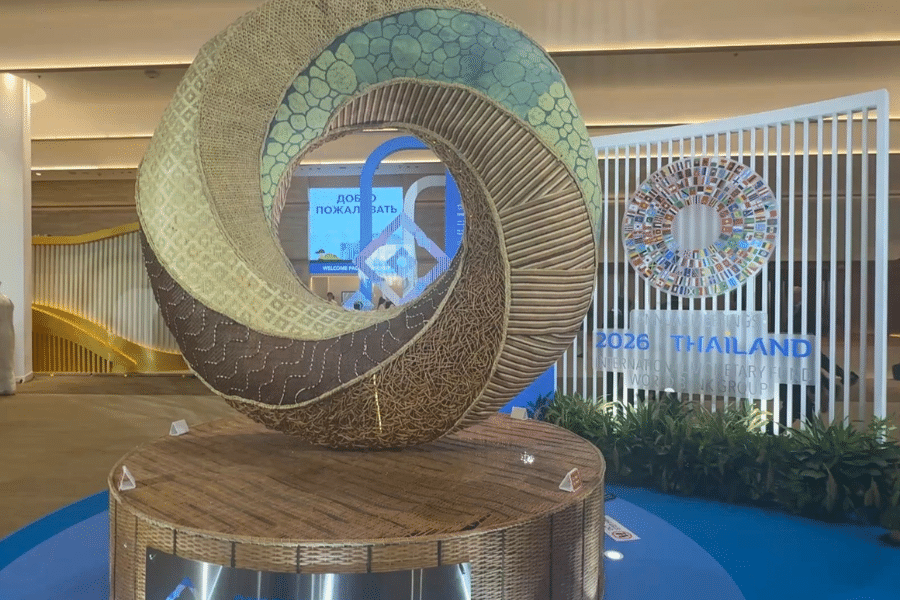
7 Unexpected Lessons from the IMF Meetings in Bangkok
22 October 2026
What attending the world's most influential gathering of economic policymakers and the financial sector taught me about access, influence, unexpected opportunities and why Africa needs more builders.
I used to organise meetings for the Standard Chartered leadership team but never attended the IMF/World Bank Annual Meetings until 2024. That year, I travelled to Washington DC as part of the Zambian government delegation. I was working on the African Development Bank (AfDB) presidential campaign and attended high-level meetings led by Zambia's Finance Minister, Hon. Situmbeko Musokotwane.
I had a green badge, which gave me access to rooms that even corporate CEOs couldn't enter unaccompanied. It was a reminder of the power and influence wielded by governments and multilateral institutions, something I had observed from the sidelines while growing up.
Fast-forward to 2026. I returned to the Annual Meetings in Bangkok, this time representing nobody but myself and ONGOLO, the advisory business I am building.
No government delegation. No corporate entourage. No impressive badge.

Just curiosity, a network built over several decades and a determination to make the trip worthwhile.
I arrived with three objectives: deepen my knowledge, expand my network and identify opportunities for ONGOLO.
Was it worth travelling all the way to Bangkok? Absolutely. But not necessarily for the reasons you might expect.
Here are my seven takeaways.
1. Access is extraordinary, even without a fancy badge
Where else can you bump into finance ministers, central bank governors and heads of multilateral institutions while queuing for food?
I went to see the Zambia delegation in the restricted area (accompanied) and to congratulate Hon. Musokotwane on his reappointment following the August 2026 general election. I also caught up with the Bank of Zambia Governor, Dr Denny Kalyalya.
Around us, finance ministers and central bank governors from other countries were grabbing a bite to eat in between meetings.
That morning, I had attended the opening workshop of the Euroclear and LSF Pan-African Bond Market Initiative (PABMI), where the Governor of the Bank of Mauritius, Dr Priscilla Muthoora Thakoor, made some excellent points. We briefly continued the discussion.

The PABMI initiative could be a real game-changer for Africa. A white paper is being drafted as a follow-up to the initiative. Watch this space.

For the rest of the week, I discovered that access isn't always about having the right badge.
In 2024, my government credentials opened doors. In 2026, it was my network.
My UK client was unable to attend the Annual Meetings and asked me to represent him at the PABMI workshop and Invest Africa event for CRDB Bank of Tanzania.

A friend at the Central Bank of Nigeria invited me to the Nigeria Investor Forum. Nigeria presented a pipeline of 65 projects seeking $78.5 billion in capital.
A long-standing friend at the Open Society Foundation invited me to Devex Impact House, where I spent half a day. I would highly recommend their gatherings for the calibre and diversity of participants.
Another friend introduced me to Hodan Osman, President of the Somali Development and Reconstruction Bank.
Somalia is laying the foundation to attract more foreign investment, with opportunities in sectors ranging from livestock exports to the Gulf to the milk industry (valued at more than $300 million), to renewable energy.
One of its most overlooked opportunities is in fishing, particularly tuna, which requires substantial investment. The best quote of the week came from Jibril Mohamed, Director of Investment and Project Implementation:
"Somalia is where fish die from old age!"
These encounters reinforced an important distinction between access and influence. A badge might get you into a room, but it is your experience, relationships and ability to contribute that determine what happens once you are there.
Lesson: Your network is a form of currency. Build it before you need it.
2. The most interesting people aren't always the most visible
I spent much of my professional career working for leading organisations in their respective fields: Shell, KPMG, Standard Chartered and the Rhodes Trust.
No explanation needed.
I was reminded of what happens when you lose the status conferred by a big corporate name when I arrived at an evening event for which I had registered weeks earlier as CEO of my own small business.
My name had been omitted from the seating plan.
I was eventually allocated a table at the back, reserved for the unassigned. At least I had an excellent view of the stage and was conveniently positioned next to a table with an apparently endless supply of Ruinart and Dom Pérignon.
A win is a win!
A European gentleman and an American woman joined me. We introduced ourselves and began discussing their rapidly expanding global business and ambitions to enter Africa.
A senior banker from a regional bank, whom I had met the previous day, came over to greet me. I offered to introduce him to my new acquaintances, but he said he would return later.
The European gentleman then made a remark that has stayed with me:
"If everyone knew we had the deepest pockets in the room, they would be lining up to speak with us." Wow.
The other person at our table was an African gemstone trader based in Bangkok. We had met during the pre-dinner reception, and he decided to join me again at dinner.
He wasn't working the room or trying to impress bankers. Yet his business has around 200 people sourcing gemstones worldwide, including diamonds from Angola, rubies from Madagascar and sapphires from Nigeria.
It reminded me how much I still have to learn about the extraordinary businesses being built by Africans, often far from the spotlight.
At conferences, we gravitate towards the people we think matter: chief executives, ministers, fund managers and investors whose names appear on the programme.
Yet some of the most commercially interesting people may be sitting quietly at the back of the room, running substantial businesses without seeking public recognition.
This is particularly relevant in Africa, where significant private enterprises and commercial networks often operate beyond the circles familiar to international financiers.
Lesson: Don't confuse visibility with influence, or appearances with wealth.
3. Knowledge is the most underrated reason to attend
Many bankers descend on the Annual Meetings, set up camp in luxury hotels and spend the week meeting clients without ever setting foot inside the convention centre.
I think this is a huge mistake.
The Annual Meetings bring together some of the world's most influential economic policymakers, financiers and thinkers. Their discussions offer invaluable intelligence on emerging risks, opportunities and the direction of global finance.
Perhaps banks should consider sending more middle-management professionals to attend the sessions and bring back strategic intelligence.
The value isn't simply in hearing what policymakers say, but in understanding how their priorities might influence capital flows, regulatory decisions and investment appetite.
And the learning isn't confined to the official programme.

At Devex Impact House, I attended a discussion where a major American bank explained how it had structured a substantial financing transaction in an African country alongside a leading development finance institution.
The following day, I had a pre-arranged meeting with a senior representative of that country's Ministry of Finance, which is seeking approximately $500 million for a hydropower project.
I shared what I had learned and explored its relevance to their financing requirements. I also established that a major French bank had no country risk appetite, helping narrow the range of potential financing partners.
Within two days, information gathered at one event had become directly relevant to a potential financing opportunity.
This is why I believe conferences should be treated as intelligence-gathering exercises, not simply networking opportunities.
Understanding who is financing what, where institutional appetite is changing and which structures are proving successful can be just as valuable as securing a meeting with a prospective client.
Lesson: Information becomes valuable when you know how to apply it.
4. The real value comes from connecting the dots
Remember the European gentleman with the deep pockets?
His business operates in digital assets, an area where he sees significant first-mover opportunities.
At the PABMI workshop, a Central Bank Governor mentioned how their country had implemented tokenisation.
Then, on Friday morning, a former banking colleague shared his view that the growth of digital assets could eventually threaten the relevance of some fiat currencies.
Three conversations. Three perspectives. One emerging theme.
I began thinking about what this could mean for African financial markets.
Could tokenisation change how assets are financed, owned and transferred? Might it help African markets attract new pools of capital? And what would it mean for financial institutions built around traditional infrastructure?
The answers are far from settled, but these are developments worth watching.
Something similar happened at the Nigeria Investor Forum.

I met representatives of Nigeria's Bank of Industry and learned more about their investment pipeline. I subsequently shared relevant opportunities with representatives of a non-African government I am keen to work with and facilitated a virtual introductory call for the following week.
Neither conversation would necessarily have led anywhere in isolation. Connecting them created an opportunity.
One of Africa's investment challenges is not always a shortage of projects or potential investors. It is often the difficulty of matching opportunities with appropriate sources of capital across borders.
Investors may lack familiarity with local institutions, regulations and risks. Governments and businesses may not know which international partners have the right mandate, expertise or appetite.
Bridging those gaps requires more than exchanging business cards. It requires understanding what each party needs and whether there is a realistic basis for collaboration.
Lesson: This is what I enjoy most about advisory work — identifying connections between seemingly unrelated conversations and turning information into opportunities.
5. Not every contact is an opportunity
I met a lot of people, exchanged numerous business cards and discussed projects across several countries.
Some conversations were genuinely exciting. Others reminded me that enthusiasm doesn't always translate into seriousness.
Running your own business teaches you to value your time differently.
In a large institution, teams, budgets and established processes support relationship development. As an independent adviser, every meeting, introduction and proposal represents a personal investment of time and resources.
You have to distinguish between an interesting conversation and a genuine opportunity.
Is there a clearly defined need? Does the person have the authority to move things forward? Is there a realistic prospect of a commercial engagement? Is the other party prepared to commit resources?
Being selective doesn't mean becoming less generous. It means being more deliberate.
Not every contact is worth pursuing. Not every introduction needs to be made. Not every request for assistance deserves a yes.
And you certainly don't need to shake every important-looking hand in the room.
Lesson: Access is valuable. Discernment is even more valuable.
6. The best opportunities are often unplanned
Looking back, some of my most productive conversations weren't on my original schedule.
They happened because someone invited me to an event, a friend made an introduction, a client needed representation or I ended up at the wrong table.
The Annual Meetings reminded me that preparation and serendipity are not mutually exclusive.
You need to do the groundwork: research participants, understand the issues, arrange meetings and know what you want to achieve.
Incidentally, I discovered that some bankers didn't even know there was a participant directory on the IMF/World Bank app. A useful resource if you want to make the most of your time!
But you also need to leave room for the unexpected.
It's tempting to fill every available hour with scheduled meetings, particularly when you've travelled a long distance and want to justify the expense.
Yet doing so can mean missing the informal conversations that make gatherings like these so valuable.
A breakfast discussion can introduce you to an unfamiliar initiative. A reception can reveal an investor's interest in a market you know well. A conversation outside your usual professional circle can challenge assumptions you didn't even realise you held.
Some of my most promising conversations in Bangkok happened simply because I was curious enough to talk to someone I didn't know.
And sometimes being relegated to the back of the room turns out to be the best seat in the house.
Lesson: Prepare thoroughly, but leave enough room for serendipity to do its work.
7. The biggest takeaway: Africa needs more builders, not just investors
One of the main reasons I attended the Annual Meetings was the launch of Vista Bank's operations in France. I met the France team when I travelled to Paris regularly in 2025 for a client engagement.
Vista Bank's founder and holding chairman, Simon Tiemtoré, spoke passionately about building and celebrating African-owned financial institutions and their contribution to development.
He recalled how, during his time at Afreximbank, financing Dangote was neither an obvious nor a universally popular proposition. Yet the bank's willingness to back African enterprise helped support the group's expansion across the continent.
He drew parallels with Guinea, which is attracting considerable investor interest today.

His remarks reinforced something I feel strongly about.
Africa cannot build its future by relying exclusively on foreign investors.
Across the continent, governments devote considerable resources to attracting foreign direct investment. Investment promotion agencies organise roadshows, governments offer incentives and international investors are courted as catalysts for economic transformation.
Foreign capital, technology and expertise undoubtedly have important roles to play.
But attracting foreign investors cannot be our only measure of success.
We also need African entrepreneurs with the ambition to build businesses that compete beyond their home markets, supported by African financial institutions willing and able to back them.
That requires an environment in which local businesses can access financing, develop technical and managerial capabilities, operate across borders and compete on more equal terms.
African businesses are not simply beneficiaries of development. They can be its drivers.
The continent needs companies capable of building infrastructure, manufacturing products, financing trade, developing technology and creating employment at scale.
Some already exist. Others are emerging in sectors and markets that international investors have yet to appreciate.
Governments must create the conditions for more of them to succeed, while financial institutions need to look beyond conventional perceptions of risk and recognise the long-term value of supporting African enterprise.
The story of Dangote and Afreximbank illustrates what can happen when African institutions back African ambition.
Lesson: We need to celebrate African companies that conquer new markets, not just foreign companies that enter ours.

Final thoughts
I am increasingly convinced that the value of attending gatherings like the Annual Meetings isn't measured by the number of meetings you secure or business cards you collect.
It's measured by what you learn, the connections you make between people and ideas, and what you do with them afterwards.
For Africa, the challenge is greater still: how do we turn the knowledge, capital and relationships assembled at gatherings like these into businesses, institutions and industries that create lasting value on the continent?
That is the question I returned home thinking about.
Bangkok was worth the trip.
Even if I now need a holiday to recover from it.
Related insights
- Private Sector - Financial Services